You opened a spreadsheet in January, color-coded every category, and swore this was the year you’d finally stick to a budget. Two weeks later you forgot to log a coffee run, felt a flash of guilt, skipped logging the next five purchases too, and by week four the whole thing was quietly abandoned. If that cycle sounds familiar, you’re in good company — and the problem probably isn’t you.
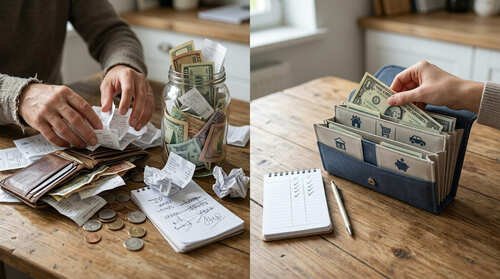
You’re Not the Only One Whose Budget Didn’t Stick
Budgets fail so often that it’s practically the industry norm, not the exception. A 2023 NerdWallet survey found that among Americans who keep a monthly budget, the vast majority admit they’ve gone over it at some point, and nearly half of that group typically covers the gap with a credit card. In other words, having a budget and sticking to a budget are two very different things.
It’s not that people don’t want structure. A national survey commissioned by Discover Personal Loans found that a large share of Americans planned to take at least one budgeting action for the year ahead, whether that meant working toward a specific goal, following a budgeting method, or using an app. The intent is there. The follow-through is where things break down.
So why does a tool that sounds so simple — track money in, track money out — collapse so often in practice? Usually, it comes down to a handful of predictable design flaws, not a lack of discipline.
Reason #1: The Budget Was Built on Guesswork
A lot of budgets start with wishful numbers instead of real ones. You estimate $300 for groceries because that sounds reasonable, not because you checked three months of receipts. Then week two arrives, you’re already over, and the whole plan feels broken before it had a real chance.
A budget built on hope instead of history is set up to fail on day one. Real numbers, even unflattering ones, give you something you can actually work with.
Reason #2: It Depends on Willpower Instead of Systems
Most budgets ask you to make the same disciplined decision dozens of times a day — every time you open a delivery app, walk past a sale, or scroll past an ad. Willpower is a limited resource, and it tends to run out well before the month does.
Systems don’t get tired the way willpower does. Automatic transfers, separate savings accounts for specific goals, and locked-in bill payments all remove the decision entirely, so there’s nothing left to resist.
Reason #3: Emotions Are Doing More of the Spending Than You Realize
This is the reason people talk about least, and it might be the biggest one. A 2025 LendingTree study on emotional spending found that most Americans say their feelings shape their purchases, and the large majority of those emotional shoppers admit it leads them to overspend. Stress, boredom, and even excitement can quietly override whatever plan was written down on paper.
In my own experience, money has never felt purely mathematical — when things are tight, the anxiety shows up almost immediately, and it bleeds into mood and confidence in a way that has nothing to do with spreadsheets. I think that’s especially true for people early in their financial lives, where money feels tied to a sense of control just as much as it’s tied to actual dollars. Naming that connection honestly, instead of pretending a budget is a purely logical exercise, is often the first real step toward making one work.
A budget that ignores the emotional side of spending is only solving half the problem. The other half is building in room for how you actually feel, not just how you think you should behave.
Reason #4: One Slip Feels Like Total Failure
Budgets often collapse the same way New Year’s resolutions do. You go over on one category, decide the month is "ruined," and stop tracking altogether. However, a single overspent week doesn’t erase the other three weeks that went fine.
Treating a budget as all-or-nothing turns a minor correction into a full restart. A more flexible mindset — this week was off, next week isn’t — keeps one bad stretch from sinking the whole plan.
Reason #5: It Was Never Updated When Life Changed
A budget built for last year’s rent, last year’s salary, or a relationship status that’s since changed will feel wrong almost immediately. As a result, people assume the method failed, when really the numbers just went stale.
Life moves faster than most budgeting templates account for. A plan that isn’t revisited every few months isn’t really a plan anymore — it’s a snapshot of a life you don’t have anymore.
How to Build a Budget That Actually Sticks
Base It on Three Real Months, Not One Ideal One
Before setting any category limit, pull up your last three months of bank and card statements. Add up what you actually spent in each area, then use that average as your starting point instead of a guess.
Automate Every Fixed Decision You Can
Set up automatic transfers to savings the same day your paycheck lands, and put recurring bills on autopay wherever possible. Because the decision only has to be made once, it removes dozens of small opportunities to derail the plan later.
Build In a Guilt-Free Category
Give yourself a small, judgment-free spending category every month — even $30 or $50 — and stop tracking it once it’s gone. Counterintuitively, this tends to reduce overspending elsewhere, since the pressure to be perfect is what usually causes the biggest blowouts.
Review It Monthly Instead of Setting It Once
Block 15 minutes at the same time each month to compare what actually happened against what you planned. Adjust the numbers that were unrealistic, and leave the ones that worked alone.
Separate the Emotional Spend From the Necessary Spend
When you notice a purchase driven by stress or boredom rather than need, don’t just shame it away. Write it down instead, since noticing the pattern is usually more useful long-term than trying to white-knuckle through the next urge.
Frequently Asked Questions
Why do I keep failing at budgeting even when I really try? Most budgets fail because of unrealistic starting numbers or an all-or-nothing mindset, not because of a lack of effort. Building the plan around your real spending history, instead of an ideal version of it, tends to fix this quickly.
Is it normal to go over budget almost every month? Yes — surveys consistently show that most people with a monthly budget exceed it at least occasionally. The goal isn’t a perfect month; it’s a plan flexible enough to absorb the occasional overspend without collapsing entirely.
How long does it take for a new budget to actually feel sustainable? Most people need two to three months of adjusting categories before a budget starts to feel realistic rather than restrictive. Give it at least one full review cycle before deciding whether the method itself isn’t working.
Should I use an app, a spreadsheet, or cash envelopes? The best system is the one you’ll actually open consistently, not the one that looks most sophisticated. If a spreadsheet feels like a chore, a simpler app or the envelope method may hold your attention longer.
A budget doesn’t fail because you’re bad with money — it usually fails because it was built for a version of your life, and your habits, that doesn’t quite exist. Fix the design, and the same numbers that felt impossible last month start to feel manageable. If you’re still working out how much of your income should go where in the first place, the 50/30/20 rule is a solid, flexible starting framework worth exploring next.